Quick answer: For collecting USD payments into India, the right rail depends on speed, cost and where your client banks. ACH is the cheapest for routine, non-urgent transfers but takes 1 to 3 business days. Fedwire and the real-time networks FedNow and RTP are far faster, settling the same day or in seconds, though Fedwire carries a per-wire fee. SWIFT is the default for international bank wires but is usually the slowest and most expensive once correspondent-bank fees and exchange-rate markup are counted. For a US-to-India business, the cheapest and best-documented route is normally a virtual USD account that collects on local US rails such as ACH, Fedwire or RTP and settles to your Indian bank in INR at the mid-market rate, with a FIRA issued automatically, rather than a direct SWIFT wire.
Introduction
India is on the brink of a significant transformation in its export sector. According to a report by KPMG1, its exports, which include both goods and services, are likely to surge from $770 billion to $1.7 trillion by 2028.
But it takes more than just an opportunity to succeed in a global market. Businesses must also tap into the right solutions, payment methods and means to navigate the global market confidently.
Every country has different local methods in addition to global wire transfers that facilitate cross-border payments. In this article, we’ll examine the India-US market and how Indian companies, regardless of their size, can leverage different payment methods to collect funds that best suit their business needs.
In this article, we'll explore different payment methods, such as ACH, Fedwire, and SWIFT. We'll also break down the differences between ACH vs Fedwire vs SWIFT, exploring how each payment network works, what makes them unique, and when to use one over the other.
Different ways to collect payments from USD to INR
Every region or country has a local payment method typically integrated within their banking infrastructure. Some examples of local payment methods outside of the US are SEPA for the European Union, PIX in Brazil, M-Pesa in Africa, CHAPS in the UK and NEFT, IMPS or UPI in India. While these methods are designed to facilitate domestic transactions, they also play a key role in receiving international payments.
When receiving international business payments from the US in India, businesses have three primary options: Automated Clearing House (ACH), Fedwire, and SWIFT. Each payment method is designed to meet different business needs, from transaction speed and cost-effectiveness to overall convenience.
The key difference between these methods is that while ACH and Fedwire are local payment methods available in the US, SWIFT is a global network.
What is an Automated Clearing House (ACH) payment?
Specifically used in the US, the ACH payment system is an electronic system that facilitates transactions in US dollars between different banks in the country. The National Automated Clearinghouse Association, or Nacha, manages this fund transfer system. It's a large group of banks, payment processing companies, and credit unions. The primary role of Nacha is to define the regulations and standards that govern the ACH network.
Further, transfers via ACH are easily traceable, helping to identify fraudulent activities easily. ACH regulations protect both the sender and the recipient, as the money is transferred directly between accounts, with the account numbers kept confidential.
How does ACH transfer work?
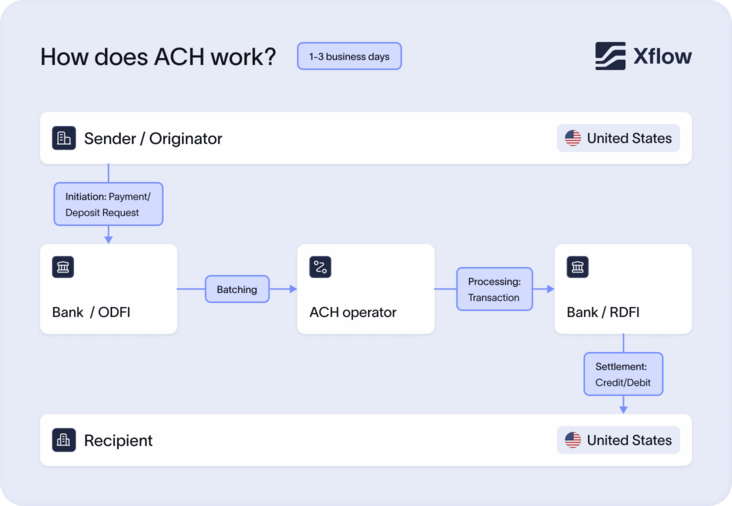
ACH allows batch transfer of payments. In simple terms, the ACH network first accumulates all payments and then sends them in a single instance. The best advantage of this type of transfer is the lesser cost it involves. However, there's a downside to this cost efficiency as well since ACH payments typically take longer to settle compared to other methods. Here's what a usual ACH payment transfer looks like:
- Initiation: The sender or originator requests a payment or deposit through their bank, known as the Originating Depository Financial Institution (ODFI).
- Batching: The ODFI collects multiple ACH requests and groups them into a batch, which is sent to an ACH operator, either the Federal Reserve or a private clearinghouse, at scheduled intervals.
- Processing: The ACH operator sorts the batch and forwards each transaction to the appropriate Receiving Depository Financial Institution (RDFI), which is the recipient's bank.
- Settlement: The RDFI credits or debits the recipient's account, completing the transfer. This process usually takes 1-3 business days. Same-day ACH is also available now for many transactions but at higher costs.
ACH vs wire transfer: what is the difference?
In the US, a "wire transfer" usually means a real-time bank wire sent over Fedwire for domestic payments or SWIFT for international ones, while ACH is a batch system that moves money between US bank accounts in scheduled cycles. The practical differences decide which one you should use:
- Speed: a wire over Fedwire settles the same day, often within minutes, while standard ACH takes 1 to 3 business days. Same-Day ACH narrows the gap for lower-value payments.
- Cost: ACH is free or a few cents, whereas a wire incurs wire transfer fees of roughly $25 to $50 domestically and more internationally once intermediary fees are added.
- Reversibility: ACH can be returned or disputed within set windows, but a wire is effectively final once it is sent.
- Reach: ACH is domestic-US with limited Global ACH options, Fedwire is domestic, and SWIFT is the international wire network.
For a one-off, urgent, high-value payment a wire wins on speed; for routine or cost-sensitive payments ACH wins. For money coming from the US into India, neither a plain ACH nor a SWIFT wire is ideal on its own: a collection platform routes the US client over local rails and handles the INR conversion and compliance for you.
ACH v/s Fedwire v/s SWIFT: A comparison of payment systems for USD to INR
Each payment method plays a crucial role in facilitating payments, but they differ significantly in speed, cost, and intended use. Local payment methods allow businesses to receive international payments more quickly, securely, and often at a lower cost than traditional global systems like SWIFT.
- Automated Clearing House (ACH) - ACH is a payment system used to move money between two US bank accounts. It was set up to address the inefficiencies in the mass sorting and processing of paper checks. Managed by the National Automated Clearing House Association (NACHA)4, ACH payments are batch-processed and cleared by a single intermediary known as the ACH operator.
- Fedwire - Fedwire Funds Service5, commonly known as Fedwire, is an electronic payment system operated by a group of twelve Federal Reserve banks in the US. Fedwire is a Real Time Gross Settlement (RTGS) system that allows participating institutions to send and receive same-day fund transfers.
- SWIFT - The SWIFT6 network, which stands for Society for Worldwide Interbank Financial Telecommunication, is the most popular system of international payments. Unlike Fedwire and ACH, SWIFT doesn’t hold funds or transfer money. Instead, it provides the messaging infrastructure that banks around the world use to talk to each other. It was founded in 1973 by a collective of 239 banks from 15 countries with the goal to create a common language for international financial messaging. The collective has since grown exponentially. SWIFT now services over 11,000 institutions around the world, spanning over 200 countries.
How does ACH work?
ACH payments are processed in batches. In case of debits, the funds are generally settled either on the same day or by the next business day, while ACH credits can take anywhere from the same day up to two business days to process the payments.
ACH payments involve a series of steps to transfer funds between bank accounts. The process begins when the sender, such as a business or employer, enters the payment details into the ACH system. The payment requests are then gathered by the sender's bank and sent as a batch to the ACH operator. After that, the ACH operator forwards the batch to the recipient's bank. Once the funds reach the recipient's bank, they are released from the sender's account and routed through the ACH network to the destination account.
Benefits of using ACH in international payments
ACH transactions have become an increasingly popular choice for businesses looking to optimize their financial operations. Below, we highlight the key benefits of ACH payments in terms of cost, time, and security.
- Cost-effective: ACH payments are electronically transmitted and passed through a single intermediary, thereby minimizing the number of steps in the transaction. This means that they cost practically nothing: The sender incurs a nominal fee (under $3) & the recipient incurs no fee.
- Secure: ACH transfers are encrypted and processed through secure networks that enforce strict regulations–making this more secure than card or wire payments. Further, transfers via ACH are easily traceable, helping to identify fraudulent activities easily. ACH regulations protect both the sender and the recipient, as the money is transferred directly between accounts, with the account numbers kept confidential.
- Reversible transfer: Banks can reverse ACH payments but must follow strict procedures and timelines. They must also notify the account holder of the reversal and provide a reason for it. Account holders can dispute a reversal if they disagree with it.
Tip: Thanks to its low cost, reliability, automation, and reversibility, ACH is best suited for low-value, non-urgent, and frequent transactions, such as paychecks and recurring bills. This is the best option for freelancers and businesses looking to get paid on a regular basis.
How does Fedwire work?
Fedwire transactions are initiated when the sender (in this case, a US-based client) provides payment instructions to its bank. The sender's bank then authenticates the transfer request, verifying the sender's identity and the transaction's legitimacy to ensure compliance with regulatory standards and prevent fraud. Once authenticated, the transfer is processed in real-time, with the Federal Reserve directing the funds to the recipient's bank. After the transfer is completed, both the sender and recipient receive a notification: the sender's bank confirms the transaction, while the recipient's bank alerts them that the funds have arrived. Unlike ACH, in the case of Fedwire transfers, both the sender and receiver have to pay a fee for collection and sending.
Key benefits of using Fedwire
- Speed: Fedwire payments are settled quickly–sometimes within hours or on the same business day.
- Security: Fedwire transactions are governed by strict regulatory standards. Both the sending and receiving banks perform multiple verification steps to ensure the accuracy of account numbers, routing numbers and the parties' identities. The chances of financial fraud are negligible.
- No limits on transactions: Well, technically, there are: the upper limit is $9,999,999,999.99 per day. This makes Fedwire ideal for high-value transactions.
Tip: Thanks to its speed, security, and lack of transaction limits, Fedwire is ideal for high-value, time-sensitive transactions. This is the best option for businesses dealing with high-value goods or services that need same-day payment.
How does SWIFT work?
At the core of the SWIFT infrastructure is the Bank Identification Code (BIC), a unique-eleven-character-alphanumeric code that describes each member bank, its location, and branch number. SWIFT codes allow banks to identify each other and transmit payment orders securely and quickly.
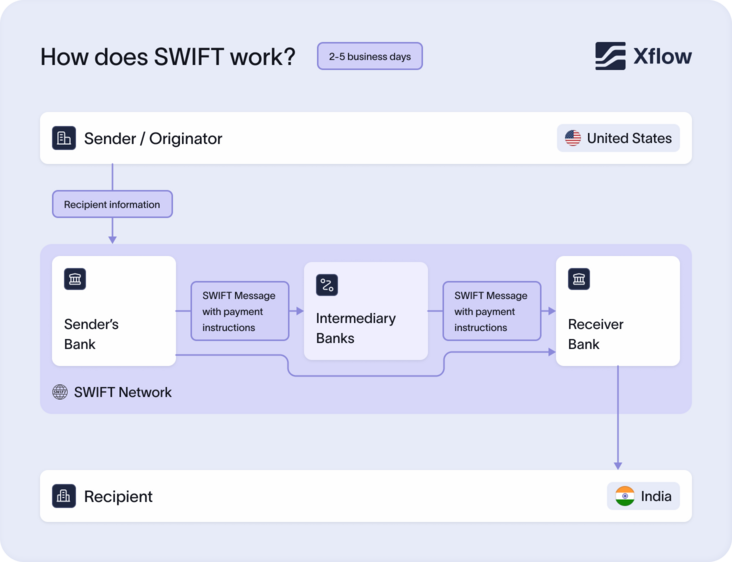
To initiate a SWIFT transaction, the sender approaches their bank after gathering the necessary details: the recipient’s bank name, address, SWIFT code, and account number. A SWIFT message containing payment instructions is then transmitted securely through the network. Upon receiving the message, the recipient’s bank verifies the information and processes the transaction. If the two banks do not have a direct commercial relationship, the payment is routed via intermediary banks, sort of like an international flight with multiple layovers.
SWIFT transfer costs and processing time
It typically takes between one and five days for transactions to be credited, with fees varying based on the transaction amount, banks involved, currency and the country. The SWIFT fees are categorised as transfer fees and intermediary bank fees. The sender is typically responsible for a transfer fee, which can range from $25 to $100, depending on the bank and the transfer amount. If intermediary banks are involved in the process, there will be additional charges, which may be paid by the sender, shared between the parties, or covered by the recipient, the latter being the most common scenario. These fees usually range from $15 to $50 per intermediary bank. The recipient may also be charged a fee, typically between $10 and $30, based on the policies of the receiving bank.
Key benefits of using SWIFT transfer:
- Highly secure: SWIFT messages and data flows are encrypted and constantly monitored to prevent unauthorized access, making the network highly secure. Chances of financial fraud are negligible.
- Extensive international reach: With over 11,000 participating financial institutions from over 200 countries and territories, spanning every continent, SWIFT is a truly global payment network. Its highly standardized system allows for seamless communication between all of these member institutions.
Where FedNow and RTP fit
ACH, Fedwire and SWIFT are no longer the only US rails. Two real-time networks now move money in seconds, around the clock:
- RTP (The Clearing House): launched in 2017, RTP settles payments in seconds, 24/7, and now supports high-value transfers. Many US banks and fintech receiving accounts, including Xflow, can collect on RTP.
- FedNow: the Federal Reserve's real-time rail, launched in 2023, also settles in seconds, 24/7. Adoption is still growing, and per-transfer limits are set by each participating bank.
Both are domestic-US rails, so a US client uses them to fund a payment into a US account. For a US-to-India business, a virtual USD account from a provider offering receiving accounts that accept ACH, Fedwire and RTP gives your client the fastest, lowest-cost way to pay, while you still receive clean INR with a FIRA.
ACH vs Fedwire vs FedNow vs RTP vs SWIFT: a quick comparison
| Metric | ACH | Fedwire | FedNow | RTP | SWIFT |
|---|---|---|---|---|---|
| Speed | 1 to 3 business days (Same-Day ACH faster) | Same day, often minutes | Seconds | Seconds | 1 to 5 business days |
| Availability | Batch cycles, business days | Business hours, Mon to Fri | 24/7/365 | 24/7/365 | Varies by bank |
| Cost (sender) | Free to a few cents | About $25 to $50 | Low, set by bank | Low, set by bank | $25 to $100+ plus intermediary fees |
| Reach | Domestic US (limited Global ACH) | Domestic US | Domestic US | Domestic US | International, 200+ countries |
| Transaction limit | Lower, varies by bank | Very high | Set by each bank | High (up to several million) | High |
| Reversibility | Can be returned or disputed | Final once sent | Final once sent | Final once sent | Final once sent |
| Best for | Routine, cost-sensitive payments | Urgent high-value domestic payments | Real-time domestic payments | Real-time domestic payments | International bank wires |
To collect USD into India, an Xflow virtual USD account accepts ACH, Fedwire and RTP, then converts at the mid-market rate and settles INR to your Indian bank account the next business day. For the full set of non-wire options, see swift payment alternatives.
Can Indian businesses receive payments using Fedwire and ACH?
This is where a Virtual Bank Account Number (VBAN) comes in. VBANs are local accounts in foreign countries that allow users to receive funds via domestic payment methods.
A VBAN is just like a regular bank account, with two key differences:
- Unlike a regular bank account, a VBAN does not have a physical existence.
- A VBAN cannot store a balance. It simply acts as a routing point, or a doorway that opens into a primary account located in India
This means that the sender (in this case the US-based client) can simply initiate a Fedwire or ACH transaction to the VBAN of the recipient (in this case an India based service exporter). Once the funds are received in the VBAN, they are seamlessly converted to INR and credited to the Indian bank account.
Frequently asked questions
ACH moves money between US bank accounts in batches over 1 to 3 business days at little or no cost. A wire (Fedwire domestically, SWIFT internationally) settles the same day but costs more and is effectively final. ACH suits routine payments; a wire suits urgent, high-value ones.
Yes. Fedwire is the main US domestic wire-transfer network, so when a US bank sends a same-day wire it usually runs over Fedwire. SWIFT is the equivalent messaging network for international wires between banks in different countries.
Both are Federal Reserve rails, but FedNow (launched 2023) is a real-time system that settles in seconds, 24/7, with limits set by each bank. Fedwire is the high-value wire system that settles the same day during business hours only.
Collecting over local US rails such as ACH, Fedwire or RTP into a virtual USD account is usually cheapest, because it avoids SWIFT intermediary fees. A platform like Xflow then converts at the mid-market rate and settles INR with a FIRA.
Not directly into an Indian bank account, but yes through a virtual USD receiving account. Xflow gives you US account details that accept ACH, Fedwire and RTP, then settles the funds to your Indian bank in INR the next business day.
A wire is faster. Fedwire settles the same day, often within minutes, while standard ACH takes 1 to 3 business days. Same-Day ACH narrows the gap for lower-value payments, and real-time rails like FedNow and RTP settle in seconds.
Conclusion
While SWIFT is the dominant payment network for international money transfers, its slow processing time, high fees and, susceptibility to fluctuating FX rates can make it frustrating for Indian recipients to collect funds from USD to INR. This leaves ACH and Fedwire as the most viable options to receive international payments, if routed via a Virtual Bank Account Number (VBAN).
Between ACH and Fedwire, the right choice depends on the business requirement:
- ACH is well suited for low value, low urgency transactions, like freelance payments and paychecks.
- Fedwire is better for high value, high urgency transactions, like export payments.
By using an Xflow Receiving Account, you can receive these payments within a few hours or instantaneously, at a favourable exchange rate, while incurring minimum overheads.